Does Insurance Cover Women’s Mental Health Treatment in California? A Complete Guide
Medical Disclaimer: The content provided in this article is for informational purposes only and does not constitute medical, legal, or financial advice. Insurance coverage for mental health treatment varies significantly based on your specific policy, provider network, and clinical medical necessity. If you are experiencing a life-threatening mental health emergency, severe panic, or active suicidal ideation, please call 988 or go to the nearest emergency room immediately. For a free, confidential verification of your insurance benefits, contact the admissions team at Sun County Wellness.
Introduction: The Financial Wall Between You and Healing
You have finally reached the tipping point. You are exhausted to your bones. The chronic anxiety, the overwhelming burnout, or the lingering trauma has made your daily life in Orange County feel like a marathon you cannot finish. You know, with absolute certainty, that you need professional help.
You find a beautiful, holistic treatment center. You see the photos of the serene gardens, the equine therapy, and the compassionate clinicians. You feel a sudden, desperate spark of hope.
And then, almost instantly, that hope is crushed by a towering wall of panic:
“How on earth am I going to pay for this?”
In California, where the cost of living is notoriously high, financial anxiety is often the number one barrier preventing women from accessing life-saving mental health care. You worry about draining your family’s savings. You assume that premium, specialized care in a place like San Juan Capistrano is a luxury reserved strictly for the ultra-wealthy who can pay out-of-pocket.
At Sun County Wellness, we want you to take a deep breath. That fear is based on a myth.
The idea that high-quality, comprehensive mental health treatment is inaccessible to the average working professional or mother is simply untrue. In reality, the vast majority of women receiving top-tier clinical care in California are doing so by utilizing their health insurance benefits.
In this comprehensive guide, we are going to dismantle the confusing, intimidating world of behavioral health insurance. We will explain your powerful legal rights under California and federal law, decode the insurance jargon (from PPOs to Out-of-Pocket Maximums), and show you exactly how to leverage your policy to find your sanctuary.
If you want to skip the reading and find out exactly what your policy covers right now, explore our free, no-obligation Insurance Verification at Sun County Wellness.
Section 1: The "Mom Guilt" and the Cost of Waiting
Before we dive into deductibles and copays, we must address the psychological barrier that stops women from using their benefits: Guilt.
Women are heavily socialized to be the financial shock absorbers for their families. You will happily pay for your child’s expensive club sports, your partner’s business expenses, or unexpected home repairs. But when it comes to spending money on your own mind and body, you freeze. You view your mental health as an “elective luxury” rather than a medical necessity.
We challenge you to reframe this mindset. Treatment is not an expense; it is the ultimate act of Asset Protection.
What is the true cost of not getting treatment?
- The Career Cost: Untreated burnout and high-functioning anxiety eventually lead to dropped balls, missed promotions, or severe medical leaves of absence.
- The Relationship Cost: Chronic, unmanaged stress is a leading driver of marital conflict and divorce—a process that carries a devastating emotional and financial price tag.
- The Physical Cost: Your body keeps the score. Unresolved trauma and chronic cortisol exposure lead to autoimmune diseases, gastrointestinal chaos, and cardiovascular issues that will ultimately cost thousands of dollars in medical bills.
Investing in your mental health is the most profound act of stewardship you can offer your family. You are securing the engine that runs your entire life.
Section 2: The Law is on Your Side (Your Legal Rights to Care)
Insurance companies often rely on consumers not knowing their rights. You have immense legal protections, especially as a resident of California.
The Federal Mental Health Parity Act (MHPAEA)
Historically, insurance companies treated mental health as a “secondary” issue. They would place severe caps on how many therapy sessions you could attend or refuse to cover intensive outpatient programs, even while offering unlimited coverage for physical ailments like cancer or diabetes.
The Mental Health Parity and Addiction Equity Act made this illegal. Under this federal law, if your health insurance plan provides coverage for physical medical needs, it must provide equal, non-restrictive coverage for mental health and substance use disorder treatment.
California's SB 855: The Ultimate Safety Net
California goes even further than the federal government to protect your mind. Passed in 2020, Senate Bill 855 is a landmark piece of legislation. It requires all state-regulated commercial health plans in California to cover all medically necessary treatment for any mental health or substance use disorder listed in the DSM-5.
Furthermore, the law dictates that insurance companies cannot use their own arbitrary, restrictive guidelines to deny care; they must use clinical standards set by non-profit medical associations (like the American Psychiatric Association).
The Takeaway: You have a legally protected right to access mental health care. Your insurance policy is a contract, and it is time to make that contract work for you.
Section 3: Decoding the Jargon (Deductibles and OOP Max)
If your insurance covers mental health, why do some people still get medical bills? To avoid “sticker shock” and understand your true out-of-pocket costs, you must master three critical insurance terms.
1\. The Deductible
This is the amount of money you must pay out of your own pocket before your insurance company starts paying for anything. For example, if your annual deductible is $2,000, you are responsible for the first $2,000 of your treatment costs. (Note: Many families have already met a portion of their deductible through regular doctor visits earlier in the year).
2\. Co-Insurance
Once you have met your deductible, you and the insurance company split the remaining costs. If you have an “80/20 plan,” the insurance company pays 80% of the daily treatment rate, and you pay 20%.
3\. The Out-of-Pocket Maximum (OOPM)
This is your ultimate financial safety net. Your OOPM is the absolute highest amount of money you will be legally required to pay in a single calendar year for covered in-network (and sometimes out-of-network) services. If your OOPM is $5,000, once your deductibles and co-insurance payments hit that $5,000 mark, your insurance pays 100% of all covered medical services for the rest of the year.
Because intensive mental health treatment is a front-loaded medical expense, many women hit their Out-of-Pocket Maximum within the first few weeks of a Partial Hospitalization Program (PHP). Once that happens, months of ongoing intensive outpatient therapy and psychiatric care are often fully covered at no additional cost to you.
Section 4: PPO vs. HMO Insurance in California
The type of care you can access largely depends on the type of insurance policy you hold through your employer or the Covered California marketplace.
PPO (Preferred Provider Organization)
If you hold a PPO plan (such as Anthem Blue Cross, Blue Shield of California, Aetna, UnitedHealthcare, or Cigna), you hold the “gold standard” for treatment flexibility.
- Out-of-Network Benefits: PPO plans typically allow you to seek care outside of their specific, crowded network. This means you can choose a premium, specialized, boutique facility like Sun County Wellness in San Juan Capistrano. Even if we are not contracted directly with your insurer, your PPO plan will still cover a significant percentage of your clinical care. This gives you the freedom to choose a program based on healing aesthetics and clinical excellence, rather than just settling for whatever sterile clinic is on a corporate list.
HMO (Health Maintenance Organization)
HMO plans (such as Kaiser Permanente) are much more restrictive.
- The Network Trap: HMOs require you to stay strictly within their pre-approved network of doctors and facilities. If you go out of network, the HMO will generally pay zero dollars. While staying in-network often results in lower out-of-pocket costs, it drastically limits your choices. You may face long wait times for therapy or be placed in overcrowded, co-ed group settings that are not conducive to trauma recovery.
- Single Case Agreements (SCA): If your HMO cannot provide the specialized care you need within their network (for example, female-specific trauma therapy or specialized equine modalities), our team can sometimes negotiate a Single Case Agreement, forcing the HMO to cover your stay at an out-of-network facility like ours.
Section 5: What Levels of Care Does Insurance Cover?
When looking at mental health treatment, your insurance does not just write a blank check for “rehab.” They authorize specific levels of care based on the severity of your clinical symptoms.
At Sun County Wellness, we operate at the precise levels of care that insurance companies recognize as intensive medical necessities:
Partial Hospitalization Program (PHP)
- What it is: Often referred to as “Day Treatment,” you attend clinical programming (therapy, psychiatry, holistic modalities) for roughly 6 hours a day, 5 days a week, but you sleep at home or in a sober living environment.
- Insurance Coverage: Highly covered. PHP is incredibly cost-effective for insurance companies because it removes the massive overhead cost of overnight “room and board” (which inpatient hospitals charge), while still delivering the intense clinical intervention required to stabilize a major depressive episode, severe trauma, or panic disorder.
Intensive Outpatient Program (IOP)
- What it is: A step-down level of care where you attend therapy for 3 hours a day, 3 to 5 days a week. It allows you to maintain your career and family life while receiving robust support.
- Insurance Coverage: Widely covered as a necessary transition phase. Insurance providers prefer IOP because it allows the patient to practice their coping skills in the real world while maintaining a strong clinical safety net, significantly reducing the risk of a relapse or future hospitalization.
Learn more about how these programs integrate into your life on our Treatment Programs Page.
Section 6: The "Medical Necessity" Battle (And How We Fight It)
You might be wondering, “If California law says they have to cover it, why do I hear stories of women getting denied?”
The answer lies in Utilization Review (UR). Insurance companies employ their own doctors to review your case and determine if your stay in a program is “medically necessary.” If they decide you are “stable enough” after two weeks, they will attempt to stop paying for your care.
This is why choosing a sophisticated facility is critical.
At Sun County Wellness, you do not have to fight your insurance company. We have a dedicated internal Utilization Review team. Our clinicians conduct “Peer-to-Peer” reviews, submitting your psychiatric evaluations, trauma assessments, and therapeutic progress notes directly to the insurance company’s doctors. We fiercely advocate for your right to heal, translating your pain into the clinical data required to authorize every single day of care you are entitled to.
Section 7: Job Protection and Paid Leave in California
A massive fear for working women in Orange County is: “If I take time off for a PHP program, will I lose my job or go broke?”
California offers some of the strongest worker protections in the nation for individuals seeking mental health care.
The Family and Medical Leave Act (FMLA) & CFRA
Under federal FMLA and the California Family Rights Act (CFRA), eligible employees are entitled to up to 12 weeks of job-protected, unpaid leave to seek treatment for a serious health condition—which explicitly includes severe anxiety, depression, and trauma recovery. Your employer cannot fire you for going to treatment, and your HR department is legally bound by HIPAA to keep your diagnosis strictly confidential.
California State Disability Insurance (SDI)
While FMLA protects your job, how do you protect your income? California is one of the few states with a robust State Disability Insurance (SDI) program. If your psychiatrist or medical doctor certifies that your mental health condition prevents you from doing your normal work duties, you can apply for SDI. This program typically pays 60% to 70% of your normal wages (up to a weekly maximum) while you are actively engaged in an intensive treatment program like PHP.
This financial bridge allows you to focus entirely on rewiring your nervous system without the crushing terror of missing a mortgage payment.
Section 8: The Sun County Wellness Advantage
When you utilize your insurance benefits at Sun County Wellness, you are not just getting standard clinical care; you are accessing a holistic sanctuary designed exclusively for the female nervous system.
While your insurance covers the rigorous medical and psychological backbone of your treatment—such as Cognitive Behavioral Therapy (CBT), EMDR for trauma processing, and psychiatric medication management—you also gain access to our unique South Orange County healing environment.
- Equine-Assisted Therapy: Utilizing the equestrian culture of San Juan Capistrano to rebuild non-verbal boundaries and self-trust.
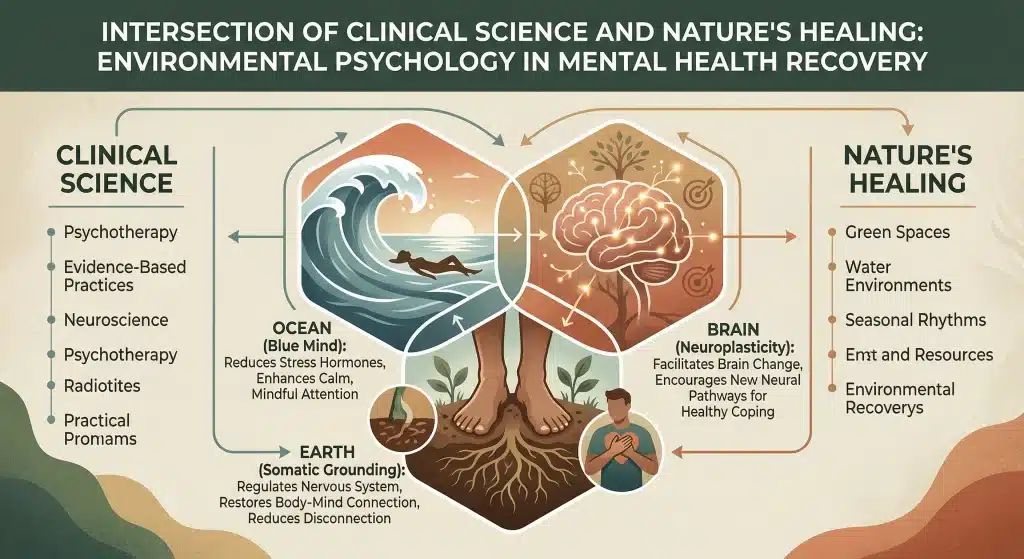
- Somatic Experiencing and “Blue Mind”: Regulating the nervous system through trauma-informed yoga, breathwork, and the healing proximity of the Pacific Ocean.
- The Sisterhood: Healing in a gender-specific environment free from the male gaze and the pressures of societal performance.
According to the American Psychological Association (APA), integrating holistic, body-based modalities with evidence-based cognitive therapy yields the highest rates of long-term recovery for complex trauma and anxiety. We provide this synthesis in an upscale, compassionate setting.
Conclusion: Stop Guessing, Start Healing
The bureaucracy of healthcare is designed to be intimidating. The disease of depression and anxiety wants you to look at the confusing insurance terms and simply give up.
Do not let an insurance company dictate your future.
You have paid your premiums every month for years. You have earned these benefits. It is time to let your policy work for you. You do not have to navigate the phone trees, the authorization codes, or the out-of-pocket calculations alone.
Let the experts at Sun County Wellness do the heavy lifting. We will cut through the red tape, decode the jargon, and show you a realistic, affordable path to reclaiming your mind and your life.
If you are ready to stop surviving and start healing, contact our admissions team at Sun County Wellness today for a 100% free, confidential insurance verification.
Frequently Asked Questions (FAQs)
Will my employer find out why I am taking a leave of absence? No. Your medical records are protected by strict federal privacy laws (HIPAA). When you apply for FMLA or a medical leave, your medical provider simply certifies that you have a “serious health condition” requiring treatment. They do not have to disclose the specific psychiatric diagnosis to your employer or HR department.
Can I attend an Intensive Outpatient Program (IOP) while still working? Absolutely. Many of our clients transition to our IOP level of care specifically so they can return to work. Attending therapy for 3 hours a day, several days a week, allows you to maintain your professional life while practicing your new coping skills in real-time with a clinical safety net.
What if I only have out-of-network benefits? Out-of-network benefits are incredibly valuable! Having a PPO with out-of-network coverage allows you to bypass crowded, sterile, in-network facilities and choose a premium, specialized sanctuary like Sun County Wellness. While your deductible might be slightly higher, the quality of individualized care you receive is exponentially better.
Does insurance cover dual diagnosis treatment (mental health and alcohol/substances)? Yes. If you are struggling with high-functioning anxiety or depression and are simultaneously using alcohol or prescription medications to cope, this is a Dual Diagnosis. Insurance providers recognize that treating both conditions simultaneously is a medical necessity and the clinical gold standard for relapse prevention.